FACT HIGHLIGHTS SUMMER CRACKDOWN ON ILLEGAL STREAMING

UK anti-piracy organisation FACT says enforcement activity over the summer has resulted in prison sentences, arrests and financial penalties against operators and users of illegal streaming services, with three recent cases involving around £1.4 million in revenue.

The largest involved Milan Ibrahim, 68, from Lancashire, who was sentenced in August to six-and-a-half years in prison after generating almost £1 million over three years from an illegal television streaming operation.

The service, initially identified by FACT and referred to the Police Intellectual Property Crime Unit (PIPCU), supplied customers in the UK and overseas, including British expatriates. A City of London Police investigation resulted in 80 streaming servers in Chorley being seized and shut down.

Content from the BBC, ITV, Sky and the Premier League was among that redistributed without authorisation.

A separate investigation begun by FACT in January 2023 identified Craig Austin, 38, of Whiston, Merseyside, as being behind a service selling unauthorised premium television subscriptions.

Austin had operated the service for more than five years and generated £205,000. FACT referred its findings to Merseyside Police in April 2025 and a warrant was executed four months later.

Austin pleaded guilty to fraud-related offences and possession of criminal property. He received a 32-month sentence, suspended for three years, together with 150 hours of unpaid work and rehabilitation activities.

In a third case, Michael Barrow was sentenced at Swansea Crown Court to three years and two months in prison after pleading guilty to three fraud offences.

Barrow continued selling illegal IPTV subscriptions and pre-loaded Fire TV sticks despite receiving a cease-and-desist notice in 2021. His service reached almost 2,000 customers and generated more than £200,000.

The prosecution was brought by the Premier League with support from FACT and the TARIAN Regional Organised Crime Unit’s Economic Crime Team.

Collectively, the three operations generated around £1.4 million.

The cases come amid continued efforts by broadcasters, sports rights holders and law enforcement agencies to disrupt the supply of pirate IPTV services rather than concentrating solely on blocking individual streams.

Research from WPI Economics commissioned by BeStreamWise estimates piracy involving sport, film and television costs the UK economy at least £1.35 billion in lost revenue annually, which it equates to 10,400 jobs.

FACT Investigations Manager Nick Sumner said the Austin case demonstrated how “intelligence-led investigations and close cooperation with law enforcement” could identify those operating illegal services and bring them before the courts.

Enforcement over the summer has extended beyond IPTV operators. FACT prosecutions involving pubs in Staffordshire and Wales resulted in licensees being ordered to pay more than £29,000 in combined fines and costs for illegally showing Sky Sports.

Investigations are also continuing in Merseyside, where four men were arrested on June 25 and 26 following intelligence-sharing between FACT and Merseyside Police. Six warrants were executed in an operation targeting suspected streaming services believed to have supplied thousands of customers.

FACT and Sky have meanwhile extended enforcement activity into Ireland. Ten suspected IPTV sellers across Carlow, Cork, Dublin, Kildare, Galway, Laois and Limerick have been served with legal warnings following joint investigations.

Cease-and-desist notices were issued to individuals suspected of supplying unauthorised access to premium television, films and live sport. The campaign also warns users of pirate IPTV services that customer information obtained during investigations may be passed to authorities.

FACT says its investigations combine open-source and human intelligence with payment information, digital trails and examination of devices. Evidence gathered by the organisation can subsequently be used to support police investigations, prosecutions or other enforcement action on behalf of broadcasters and rights holders.

Source: broadbandtvnews.com

THE CREATIVE EUROPE MEDIA PROGRAMME CELEBRATES ITS 35TH ANNIVERSARY

The Creative Europe MEDIA programme will celebrate its 35th anniversary in 2026. Since its inception in 1991, it has played a key role in the development of the European film and audiovisual industry and has supported creators, producers, distributors and audiences of European works.

For more than three decades, the MEDIA Programme has contributed to enhancing the cultural diversity of European cinema and strengthening cooperation between European countries. The programme supports market development, facilitates the international distribution of European productions and helps European audiovisual companies to build a competitive and sustainable position in the global market.

The Czech Republic has been participating in the programme since 2002.

Enter the competition to win European films!

The KE MEDIA office, in collaboration with DaFilms.cz, is organising a competition on Facebook called ‘35 Years = 35 Films for You’, featuring 35 films supported by the KE MEDIA programme. The competition for vouchers to watch European films online takes place every Monday and runs until the end of 2026.

 35 years of supporting European audiovisual content

Since its inception, this programme has pursued two key objectives: to promote cultural diversity in Europe and to strengthen the competitiveness of the European audiovisual industry.

The MEDIA programme is constantly adapting to the evolving market – the development of new technologies, new distribution models and changing ways in which audiences consume content. Currently, support is being extended not only to film and television, but also to video games, immersive projects (XR), innovation and new forms of content production and distribution.

The MEDIA programme remains one of the most important tools supporting the development of the European audiovisual sector – both within Europe and beyond. In a world of dynamic technological and market changes, the programme helps to keep European stories moving and to reach new audiences.

Source: kreativnievropa.cz

CANAL+ AND LALIGA SIGN ANTI-PIRACY ALLIANCE COVERING 50 COUNTRIES

CANAL+ and LALIGA have signed a strategic anti-piracy agreement covering almost 50 countries across Europe, sub-Saharan Africa and Haiti, expanding their long-standing commercial relationship into a coordinated effort to combat illegal sports streaming.

The agreement will see the broadcaster and the Spanish football league share intelligence, coordinate enforcement strategies and combine technology and operational expertise to tackle piracy networks operating across multiple territories.

The partnership builds on CANAL+’s long-standing distribution of LALIGA competitions in France, Europe, Africa and Haiti, but extends cooperation beyond media rights into the protection of sports content.

Both organisations said piracy has become one of the biggest threats to the sports industry, reducing revenues that support clubs, youth development and investment in broadcast production. They also warned that illegal streaming services expose consumers to risks including malware, fraud and personal data theft.

Maxime Saada, chief executive of CANAL+, said the scale of the agreement reflected the importance the company places on tackling content piracy. He added combining the organisations’ expertise would strengthen enforcement capabilities and called on the wider sports and audiovisual industries to take similar action.

LALIGA president Javier Tebas said piracy could not be tackled by individual organisations acting alone. He said the partnership would combine technology, intelligence and operational expertise to protect the value of the league’s competitions, broadcasters’ investments and the long-term sustainability of football.

Source: broadbandtvnews.com

OMDIA STUDY: PIRACY IS NO LONGER JUST A SECURITY ISSUE — IT ALSO THREATENS THE PROFITABILITY OF STREAMING SERVICES

The television and streaming market continues to grow, but its economics are becoming increasingly strained. While the cost of premium content and sports rights remains high, market growth is being driven to an increasing extent by streaming models that generate lower revenue per viewer. The Omdia study Next-Generation Anti-Piracy for TV and Video: Why the streaming era demands a shift from reaction to prevention therefore warns that piracy can no longer be viewed solely as a technical or legal issue. It is having an increasingly significant impact on revenues, operating costs and the return on investment in content.

Published by research firm Omdia in July 2026, the study examines piracy in the context of the broader transformation of the economics of the television and online video market. On the one hand, service providers must finance expensive programming and premium rights; on the other, they face pressure on profitability and changes in the revenue mix. According to Omdia, it is precisely in this environment that the role of content protection is changing, moving from a supporting security function to a strategic business priority.

The economic dimension of the problem is further amplified by the profile of those consuming pirated content. Omdia points out that nearly half of the highest-spending and most engaged viewers are also among the most active consumers of pirated content. Piracy therefore has a significant impact even on audiences that are of exceptional commercial value to service providers.

The market is growing, but the revenue mix is changing

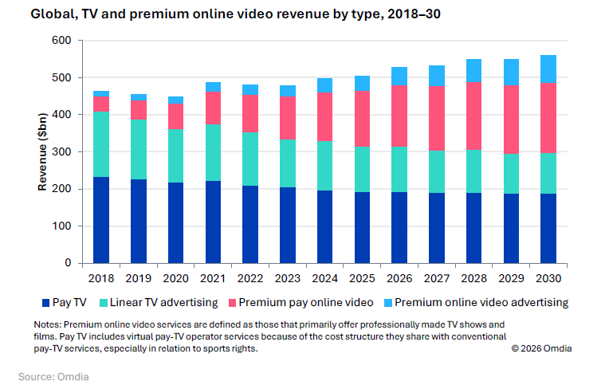
At first glance, the outlook for the industry appears relatively positive. Omdia forecasts that global television and premium online video revenues will increase from approximately USD 504 billion in 2025 to more than USD 560 billion in 2030. However, growth in the market’s overall value does not tell the whole story. It is equally important to consider where the new revenue is coming from.

According to the study, pay-TV subscription revenues and linear television advertising revenues are declining. Growth is increasingly concentrated in ad-supported streaming tiers and other online video formats, which on average generate lower revenue per viewer. The overall market can therefore continue to grow even though part of that growth comes from business models that generate less revenue per user.

The chart below shows the development of global television and premium online video revenues between 2018 and 2030, broken down into pay TV, linear TV advertising, paid premium online video and premium online video advertising.

Source: Omdia

These changes are highly relevant to the discussion around piracy. In addition to pursuing further growth, service providers are placing increasing emphasis on profitability and on their ability to monetize audiences effectively. Protecting content revenues is therefore becoming increasingly important at a time when the economics of the entire industry are under growing pressure.

Premium content still comes at a high cost

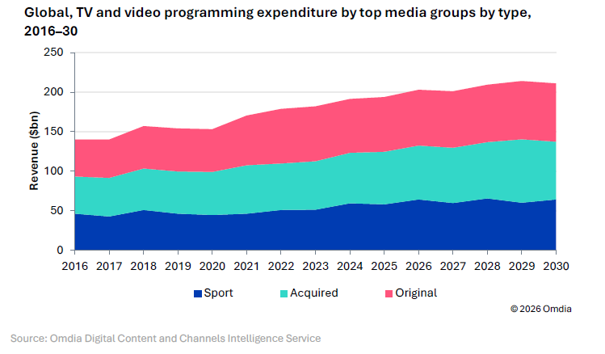
Costs, meanwhile, continue to rise. Omdia expects content spending by major media groups to reach a record USD 203 billion in 2026 and increase to USD 211 billion by 2030. Of that amount, rights to live sports alone are expected to account for USD 73 billion in 2030.

This creates a challenging combination for providers: the content they need to attract and retain viewers remains extremely expensive, while an increasing share of revenues is being generated in an environment with lower revenue per user. Piracy is therefore not only a question of content ownership, but also of whether multibillion-dollar investments in that content can generate an adequate return.

Source: Omdia

The chart shows global television and video content spending by leading media groups between 2016 and 2030, broken down into sports, acquired content and original productions. Together with the previous chart, it clearly illustrates the fundamental economic pressure facing the industry: the revenue mix is changing, while content costs remain high.

Sports are exceptionally valuable — and expensive

According to Omdia, the high level of spending on sports rights has a clear economic rationale. Sports help attract new subscribers and reduce churn. Because most sports coverage is watched live, it can also bring together a mass audience at a single moment, making it exceptionally valuable for advertising and sponsorship.

The development of sports rights prices is not uniform across all countries — growth is slowing in some markets while accelerating in others — but sports remain one of the most significant budget items for operators. This makes the impact of live sports piracy particularly acute: it affects content in which providers invest exceptionally large sums with the expectation that it will attract new subscribers and generate advertising and sponsorship revenue.

With live sports, minutes matter

Omdia identifies live restreaming as one of the defining threats of the current era of piracy. Live content is illegally redistributed in real time through pirate CTV services, social platforms, dedicated websites and apps. According to the study, this is where the financial risk is highest and where the scope for reactive intervention is most limited. By the time a takedown request for an illegal stream is issued, the match may already be over and the associated revenue lost. In this context, piracy affects the product precisely at the moment when it has the greatest commercial value to the rights holder.

When the operator also bears the cost of the pirate stream

The study illustrates the economic impact even more clearly using the example of abuse of a legitimate provider’s distribution infrastructure, known as CDN leeching. Attackers can obtain stolen access tokens from legitimate applications and use them to pull the stream directly from the operator’s network. As a result, content may be delivered to non-paying viewers through the same infrastructure that the provider finances for its legitimate customers.

According to Omdia, this type of abuse has a threefold impact. First, it increases the operator’s data delivery costs, as the provider is effectively paying to distribute content to non-paying viewers precisely during periods of peak demand. Second, the additional load may degrade service quality for legitimate subscribers. Third, it reduces the return on investment in premium content. Piracy therefore not only lowers the return on investment in premium content, but can also directly increase operating costs.

Content protection is moving from IT into strategic management

According to Omdia, the growing economic significance of piracy is also reflected in the priorities of media companies themselves. More than half of technology executives at television, film, sports and online video providers consider content protection — including technologies and measures such as digital watermarking, anti-piracy tools, application security and controls designed to limit unauthorized credential sharing — to be a highly significant business challenge.

Content protection is therefore moving onto a similar level of importance as other major issues facing the media industry, such as the adoption of artificial intelligence, cloud migration and the convergence of traditional television broadcasting and streaming. Its role is changing: it is no longer simply about securing content delivery, but increasingly about protecting revenue, content investment and the economics of the service itself.

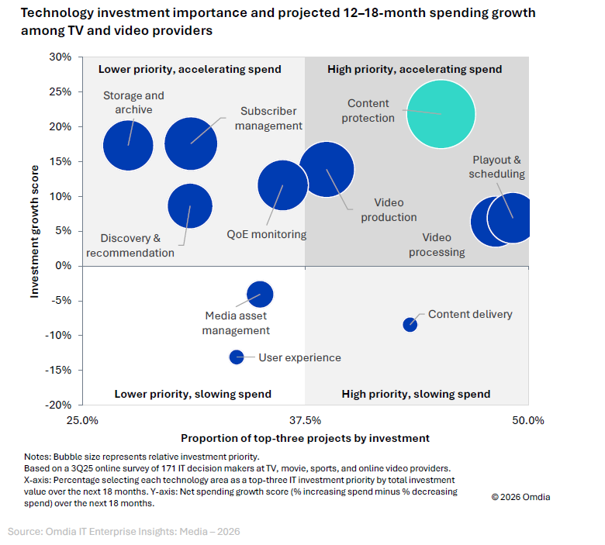
This shift is also reflected in investment plans. In a survey of 171 IT decision-makers at television, film, sports and online video providers, Omdia examined technology priorities and expected spending trends over the following 12 to 18 months. In this comparison, content protection ranks among the areas with both a high investment priority and growing expenditure. In terms of investment momentum, it ranks ahead of areas such as user experience, subscriber management, and content discovery and recommendation systems.

Source: Omdia

The chart shows that content protection is both a high-priority investment area and one in which providers expect spending to continue to increase.

Content protection is becoming part of investment protection

Against a backdrop of rising content costs, pressure on margins and pirate services that can now compete even in terms of user experience, perceptions of security are also changing. If content protection is viewed merely as a technical cost item, its business value can easily be overlooked. Omdia, however, takes a different view: content protection is increasingly also about protecting the revenue and the investment in the product for which the operator has paid.

Omdia therefore recommends that television and online video service providers treat content protection as a strategic priority. According to the study, underinvestment in this area carries the risk of losing not only revenue, but also the viewers whom investments in premium content were intended to attract and retain. From this perspective, combating piracy is no longer simply a matter of securing content; it is also about protecting the service’s business model.

According to the study, reactive measures alone are no longer sufficient. Modern piracy can exploit their limitations, and particularly in the case of live content, reactive intervention often comes too late. If revenue protection is to be truly effective, part of the defensive strategy must shift from identifying and removing illegal content after the fact to prevention — in other words, preventing attackers from obtaining the content in the first place and subsequently redistributing it. This shift from reaction to prevention will be the focus of the third part of the series.


About the study: Next-Generation Anti-Piracy for TV and Video: Why the streaming era demands a shift from reaction to prevention was published in July 2026 by research firm Omdia. Its authors are Rob Gallagher, Principal Analyst for Consumer Technology and Services, and Rik Turner, Principal Analyst for Cybersecurity. The study was commissioned by Verimatrix and, in addition to examining the transformation of piracy in the streaming era, explores why the authors believe traditional reactive content protection tools increasingly need to be combined with preventive security mechanisms. The analysis draws on Omdia’s ongoing research into television and online video, digital content, consumer behaviour, cybersecurity and enterprise technology. The consumer data used in the study includes, among other sources, an online survey conducted in November 2025 among 21,806 people aged 18–64 in Australia, Brazil, France, Germany, Japan, Mexico, Spain, the United Kingdom and the United States. Data on the reasons for using unauthorized video services is based on responses from 4,499 respondents across the same nine countries.


Source: verimatrix.com

PRŮZKUM: ČEŠI NEVNÍMAJÍ REKLAMU JAKO HLAVNÍ FAKTOR SPOTŘEBY ALKOHOLU

Většina Čechů se domnívá, že reklama nemá zásadní vliv na množství vypitého alkoholu. Za největší problémy spojené s alkoholem považují řízení pod vlivem, prodej alkoholu nezletilým a nedostatečné vymáhání platných pravidel. Vyplývá to z průzkumu agentury Ipsos pro Radu pro reklamu.

Většina Čechů si nemyslí, že reklama zásadně ovlivňuje množství vypitého alkoholu. Za největší problémy spojené s alkoholem naopak považují řízení pod vlivem a prodej alkoholu nezletilým. Vyplývá to z průzkumu agentury Ipsos pro Radu pro reklamu, který zjišťoval postoje veřejnosti ke konzumaci alkoholu, regulaci a samoregulaci reklamy.

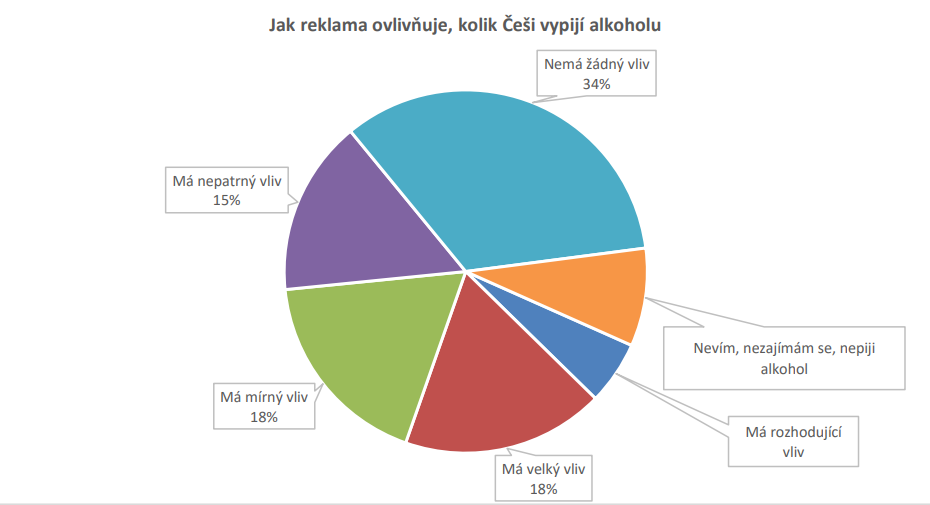
Podle výsledků průzkumu považuje polovina respondentů vliv reklamy na množství zkonzumovaného alkoholu za nulový nebo pouze nepatrný. Pouze šest procent dotázaných označilo reklamu za rozhodující faktor ovlivňující spotřebu alkoholu.

Průzkum zároveň ukázal, že veřejnost za nejzávažnější problémy spojené s alkoholem považuje především rizikové chování a nedodržování stávajících pravidel. Za závažný problém označilo 92 % respondentů řízení pod vlivem alkoholu. Následuje prodej alkoholu osobám mladším 18 let a nadměrná konzumace alkoholu, které jako problematické vnímá shodně 87 % dotázaných. Konzumaci alkoholu nezletilými považuje za závažný problém 85 % respondentů a nedostatečnou kontrolu dodržování zákonů při prodeji alkoholu 82 %.

Tomu odpovídají i preference navrhovaných opatření. Největší podporu získaly častější policejní kontroly řidičů zaměřené na alkohol, které by uvítalo 42 % respondentů. Dále lidé podporují důslednější kontroly prodeje alkoholu nezletilým a přísnější postihy za porušování pravidel v této oblasti, obě opatření podpořilo 38 % dotázaných.

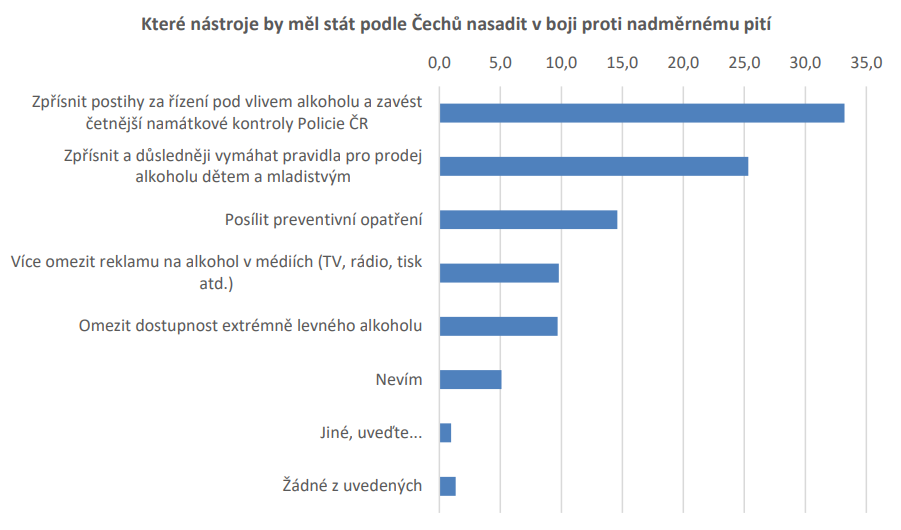
Pokud by se stát měl zaměřit pouze na jednu oblast, třetina respondentů by upřednostnila zpřísnění postihů za řízení pod vlivem alkoholu a častější namátkové kontroly. Dalších 25 % by se soustředilo na důslednější vymáhání pravidel při prodeji alkoholu nezletilým. Omezení reklamy na alkohol označilo za prioritu přibližně deset procent dotázaných.

Průzkum se zaměřil také na samoregulaci reklamy. Za smysluplný nástroj pro nastavování a kontrolu pravidel ji označilo 55 % respondentů. V oblasti reklamy na alkohol funguje samoregulace vedle zákonných pravidel a podle Rady pro reklamu umožňuje nastavovat přísnější standardy, než jaké vyžaduje legislativa.

Zdroj: Průzkum „Regulace konzumace alkoholu“, Ipsos pro Radu pro reklamu, srpen 2026, 1042 respondentů


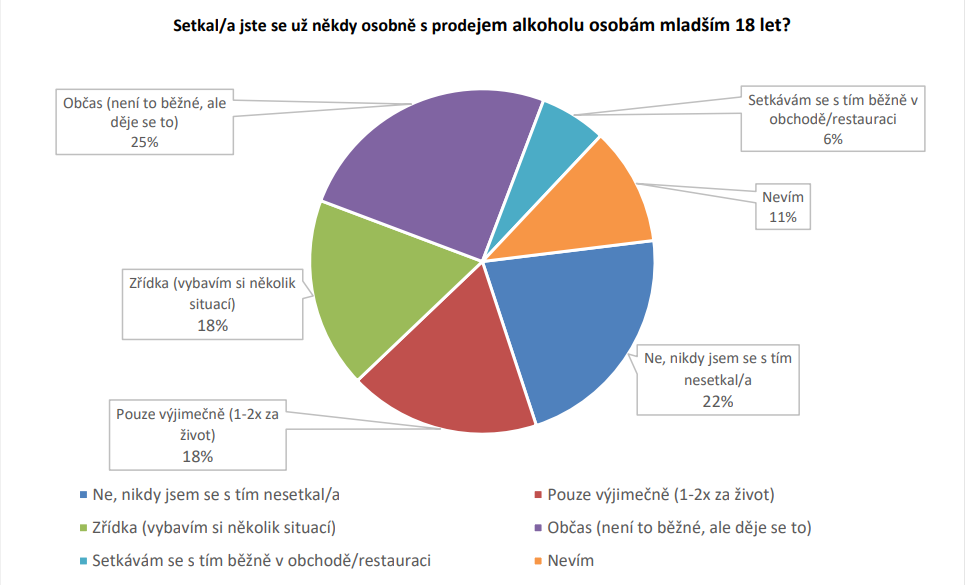
Zdroj: Průzkum „Regulace konzumace alkoholu“, Ipsos pro Radu pro reklamu, srpen 2026, 1042 respondentů

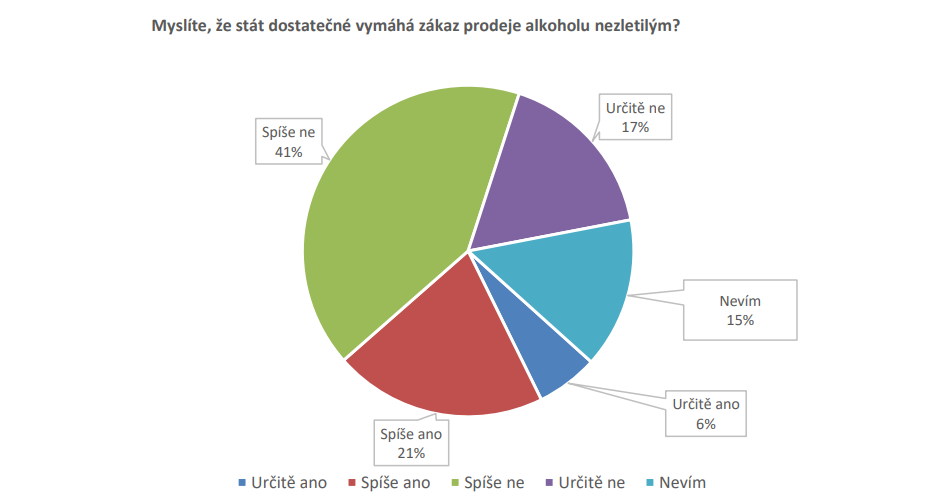
Zdroj: Průzkum „Regulace konzumace alkoholu“, Ipsos pro Radu pro reklamu, srpen 2026, 1042 respondentů

Zdroj: Průzkum „Regulace konzumace alkoholu“, Ipsos pro Radu pro reklamu, srpen 2026, 1042 respondentů

Průzkum agentury Ipsos pro Radu pro reklamu byl realizován v srpnu 2026 na vzorku 1042 respondentů. Je ke stažení zde.

Zdroj: mediaguru.cz

CZECHS WANT CERTAINTY ABOVE ALL ELSE FROM AI. SIX OUT OF TEN USERS HAVE DOUBTS ABOUT THE ACCURACY OF THE OUTPUTS

Around two-thirds of adult Czechs currently use artificial intelligence. Although most of them have a positive attitude towards it, the question remains as to how much they can trust its answers. According to a survey by the STEM/MARK agency, 60 per cent of AI users are unsure whether the output they receive from the tool is actually correct. According to the survey results, users would therefore appreciate it if AI could distinguish more clearly between verified information, estimates and situations where it is simply unsure.

According to the research, 85 per cent of AI users have a positive attitude towards it. They also use it more frequently and for a wider range of tasks, such as searching for information, obtaining practical advice, translations, generating images or working with technical information. Conversely, people with a negative attitude towards AI use it less frequently and for a narrower range of activities.

Trust is not just a matter of satisfaction

Doubts about the accuracy of answers are not, however, a problem exclusive to those who have a negative attitude towards artificial intelligence. 61 per cent of users with a positive attitude towards AI lack confidence that they can trust the AI’s output. Among users with a negative attitude, the figure is 52 per cent.

The link between trust and satisfaction is also interesting. The need for certainty regarding accuracy is cited more frequently by people who are satisfied with AI outputs. The answer may therefore be useful and well-formulated for the user, yet they may still be unsure whether the information it contains is correct. According to STEM/MARK, satisfaction decreases more significantly only when doubts about credibility are combined with the use of out-of-date data.

Users want to know where the answer comes from

The survey results also point to a desire for greater transparency. According to STEM/MARK, it would help users, for example, to be able to distinguish whether the AI has taken the information from a source, calculated it, derived it from available data, or whether it is general knowledge or merely an estimate. It is also important to know the time period to which the answer relates and how up-to-date the data used is.

It is precisely the ability to acknowledge uncertainty that may be one way of strengthening trust in AI. However, estimating uncertainty is not the same as verifying truthfulness. Language models are primarily trained to generate responses that match the prompt and are useful and plausible to the user. This does not, in itself, mean that they are factually correct.

Critical assessment of the outputs therefore remains, for the time being, the responsibility of the person using the AI. Verifying information and the ability to recognise potential errors therefore remain an important part of working with artificial intelligence tools.

The STEM/MARK survey was conducted in July 2026 via an online questionnaire on the National Sample panel. It involved 506 participants representing the internet population aged 18 and over, stratified by gender, age, education, region and size of place of residence.

Source: mam.cz

IRDETO AND CHAINALYSIS STRENGTHEN ANTI-PIRACY PARTNERSHIP

Irdeto and blockchain data specialist Chainalysis are strengthening their partnership to tackle digital piracy and cryptocurrency-enabled cybercrime.

The companies are combining blockchain intelligence, payment disruption and international law enforcement coordination to target pirate IPTV, streaming and gaming operations.

Irdeto says its Cyber Services team can use Chainalysis Reactor to trace cryptocurrency transactions, identify exchange cash-out points and map financial links between pirate operators.

The partnership contributed to a Europol-led operation in November 2025 involving law enforcement agencies from more than 15 European countries. It identified 69 piracy-related sites, traced around $55 million (€46.9 million) in cryptocurrency transactions and referred 25 illicit IPTV services to major cryptocurrency exchanges for disruption.

Irdeto says its investigations over the past year indicate that cryptocurrency now represents around 20% of payment methods offered by digital pirates.

Mark Mulready, VP of Cyber Services at Irdeto, said cryptocurrency has become central to the increasingly sophisticated criminal piracy business, adding that the partnership enables investigators to “follow the money” and expose the networks behind these operations.

Chainalysis says blockchain transactions are highly traceable when investigators have the appropriate tools, allowing suspicious transaction patterns and wallets linked to illicit activity to be identified.

The companies say their collaboration is aimed at helping rights holders, broadcasters, sports leagues and streaming platforms disrupt pirate businesses at both their operational and financial levels.

Source: broadbandtvnews.com

FUTURE DEVELOPMENTS WILL DETERMINE WHETHER—AND FOR HOW LONG—NOVA REMAINS ON TERRESTRIAL TV

Nova Media Group closely monitors technological developments and the market shares of individual television platforms. It reviews the situation every six months. In an interview with MediaGuru.cz, TV Nova CEO Daniel Grunt also discusses the current position of the Oneplay service and its near-term development.

Terrestrial television broadcasting remains an important part of the distribution strategy for Nova Group, although its significance has been declining over the long term. TV Nova CEO Daniel Grunt told MediaGuru.cz that the company continuously evaluates developments in the share of terrestrial distribution and will use this as the basis for deciding on any future changes. At present, Nova has no plans to change either its distribution model or the way its Oneplay streaming service operates. Instead, it intends to continue developing Oneplay primarily through content, technological improvements and enhancements to the user experience. At the same time, Grunt acknowledges that if the importance of free-to-air broadcasting continues to decline, new approaches to content may also become an option in the future. “Everything will depend on how quickly the importance of terrestrial broadcasting declines,” he says.

Can you disclose how long your distribution agreement with České Radiokomunikace for broadcasting your channels terrestrially runs for? Unless it is confidential, how long is the agreement that came into effect sometime in 2020 or 2021?

I’m afraid that is commercially confidential, so I can’t comment on it.

I’m asking because you will certainly have noticed the major distribution change that your direct competitor, Prima Group, is planning. Does Nova have a plan for how terrestrial broadcasting will develop going forward?

The plan is very simple. It depends on the weight terrestrial broadcasting carries as a major source of revenue within our distribution mix. At the moment, it is still significant, accounting for around 35 to 36%. Television advertising also continues to be a crucial source of revenue for us. Its share is gradually declining, but it still stands at around 50%. If its importance were to begin declining significantly—which I don’t think will happen—we would of course reassess the situation. At present, however, we see no reason to make any changes.

So this is not something you expect to have to address in the next few years. I’m also asking because 2030 is often mentioned as a milestone for the future of terrestrial broadcasting, as that is when the frequencies allocated by the Czech Telecommunications Office to nationwide networks are due to expire. So nothing will change before then?

I can’t guarantee that. As I said, everything will depend on how quickly the importance of terrestrial broadcasting declines. Just a few years ago, it accounted for more than 50%; today, if I remember correctly, it is around 35%. That is a relatively rapid decline. We therefore review the situation every six months and adjust our strategy accordingly. So we cannot say that anything is guaranteed for the next five or six years. Everything will depend on how strong terrestrial broadcasting remains.

And you still cannot disclose the year until which the current agreement with České Radiokomunikace remains in force?

I can’t.

Nova is strong in both pillars, free-to-air and premium content. Are you considering moving some free content behind a paywall at some point in the future?

That is one of the potential scenarios and, as I said at the beginning, it will all depend on how the decline in terrestrial distribution develops going forward.

Moving some free content behind a paywall is one of the possible scenarios for the future. The key factor, however, will be the further development of terrestrial distribution and the pace of its decline.

As far as Oneplay is concerned, its offering has long since expanded beyond early releases of Nova’s original titles and Oneplay Originals, with some fairly attractive acquisitions now appearing on the service as well.

A lot of that has to do with the strength of the Oneplay subscriber base itself. We are the largest streaming service in the Czech Republic, so we need to offer the broadest and most diverse range of content possible and appeal to as many target groups as we can. That is the only way we can continue to grow. Our goal remains to bring Czech viewers the very best content, whether that means Czech productions or acquired titles selected specifically with Czech audiences in mind.

What are your customer satisfaction surveys currently telling you? How do customers perceive Oneplay in 2026, and what do they expect from it?

I have to say that in the 15 months since Oneplay launched in March 2025, perceptions of the brand have changed dramatically. The beginning was challenging, of course. Users of both Voyo and O2 TV moved from services they were familiar with to a new platform with a new user interface and a new brand. On top of that, the price increased. But the situation began to turn around quickly. What helped us above all was the content we offer on Oneplay and the way we present it to users. We try to make it easier for them to navigate the service and help them find exactly what is relevant to them. At this point, Oneplay’s NPS is already approaching the levels achieved by Voyo, which was a much-loved brand (NPS = Net Promoter Score, a metric indicating how well regarded a service is based on customers’ willingness to recommend it, editor’s note.).

What does that score tell you in practical terms?

NPS tells us how likely you are to recommend a particular service or product to people you know. It is measured on a scale from 0 to 10, with the resulting score ranging from minus 100 to plus 100. Scores of 9 and 10 are positive, 7 and 8 are neutral, while scores of 6 or below count negatively. So it is a fairly strict metric. We are currently achieving strongly positive scores.

Are you considering offering Oneplay to operators as part of a bundled package, as Netflix, Disney+ or HBO Max do, for example?

We are not considering changing the distribution model. At present, Oneplay has two operators. Nova operates the so-called B2C customer base, meaning customers who subscribe directly, while O2 serves customers of O2 services. So we have these two operators, and we do not plan to change that.

Your competitor Prima announced an agreement with BBC Studios on 10 August that will allow it, as well as T-Mobile, to offer the BBC Player service in the Czech Republic. Are there any companies, whether global players or multinational groups, with which you are considering taking a similar approach, or are you pursuing a different path?

There is a broad range of potential partners we are considering. We are in talks with some of them, we have ended discussions with others, and we continuously assess further opportunities. It always depends on the specific commercial terms and whether a particular partnership makes sense for us. Discussions are therefore ongoing, but at this point we have not concluded any agreement.

Is there anything that is already close to being finalised?

Not at this point.

Are you planning any technological upgrades for Oneplay or anything else that would affect how the service operates going forward? I mean features such as multilingual audio, subtitles and so on.

That particular feature has actually been available on Oneplay since launch, although it was not available on Voyo. The reason it is not available for all content has to do with licensing rights and content suppliers. A large proportion of the titles on Oneplay are still governed by contractual terms negotiated back in the Voyo era, when multilingual audio, for example, was not included in the agreement. Or the supplier simply does not have additional language versions available. We therefore have to renegotiate these terms gradually and then add the relevant audio tracks or subtitles.

And will there be any other technological upgrades?

Technological upgrades are happening continuously; it is a never-ending process. As far as changes that customers will actually see are concerned, we will be improving the user interface during the second half of the year. That will be one of the most significant visible changes.

What exactly does that mean? What will be changing?

We will be redesigning the home page to make it even cleaner and easier to navigate, so viewers can find what they are looking for more easily. One of the key issues for us—and something we see as one of the biggest problems facing the entire industry—is that viewers find it very difficult to navigate the sheer amount of content available. They are overwhelmed by choice. At Oneplay, we therefore want to do everything we can to make choosing content as easy as possible. That means improving both the user interface and the recommendation algorithm, which we develop and refine ourselves. The aim is to reduce the amount of time viewers need to decide what they want to watch.

Source: mediaguru.cz

ILLEGAL STREAMING COSTS UK ECONOMY £1.35BN A YEAR, REPORT FINDS

Illegal streaming is costing the UK economy at least £1.35 billion a year and is linked to the loss of more than 10,000 jobs, according to a report commissioned by anti-piracy initiative BeStreamWise.

The Price of Piracy, produced by WPI Economics, estimates that piracy across sport, film and television results in 10,400 fewer jobs across the economy. Of these, 4,200 are in broadcasting and media production, with a further 6,200 in related sectors including advertising, publishing, retail and the wider creative industries.

The report also puts the annual loss in tax revenues at £366 million. BeStreamWise said this is equivalent to the cost of employing around 9,400 qualified NHS nurses, providing 140 million free school meals or funding 43 million childcare hours.

BeStreamWise is calling for a coordinated response from government and industry, including greater consumer awareness of the risks associated with piracy and measures to make illegal services more difficult to find and access.

Sir John Whittingdale MP, chair of the All-Party Parliamentary Group for Intellectual Property, said the findings should be a “wake-up call” for government and Parliament.

“This report provides concrete evidence that piracy costs the UK economy more than £1 billion every year and jeopardises thousands of creative industry jobs,” he said. “It also directly exposes consumers to the risk of fraud.”

Matt Hibbert, Group Director Anti-Piracy at Sky, said illegal streaming diverts money from investment in British television, film and sport, while exposing consumers to fraud, scams and identity theft.

The report argues that lost income limits broadcasters’ ability to reinvest in new programming and independent production. It also notes that sports-rights revenues help fund women’s sport, grassroots participation and talent development.

Liz Bales, Chief Executive of the British Association for Screen Entertainment, said tackling piracy requires a more integrated approach as viewing habits and piracy tactics evolve.

Source: broadbandtvnews.com

FRIEND MTS AND AGILETV INTEGRATE CDN WATERMARKING TO SPEED ANTI-PIRACY DEPLOYMENTS

Friend MTS and AgileTV have completed the first integration of AgileTV’s content delivery network (CDN) with Friend MTS’ server-side watermarking technology, allowing operators to deploy premium content protection more quickly.

The pre-integrated solution combines Friend MTS’ watermarking platform with the AgileTV CDN, enabling operators using either technology to add the other with reduced integration effort. The companies say the approach is designed to accelerate deployment while maintaining video quality for premium live sports and entertainment services.

When combined with Friend MTS’ piracy monitoring platform, the solution enables operators to identify subscriber accounts used to source illegal streams and, if required, automatically disable those accounts in real time.

The integration uses server-side A/B watermarking, with the AgileTV CDN generating uniquely watermarked streaming sessions based on subscriber session tokens. This allows pirated streams to be traced back to individual subscriber accounts without affecting the viewing experience.

The companies will demonstrate the joint solution at IBC2026, showing how subscriber-level watermarking supports rapid piracy detection and enforcement.

This announcement reflects a wider industry trend towards embedding content protection directly into video delivery infrastructure rather than treating it as a separate system.

Server-side watermarking has become increasingly important as sports rights holders demand stronger anti-piracy measures. Unlike DRM, which aims to prevent unauthorised access, forensic watermarking enables operators to identify the source of leaked streams after they appear online.

Source: broadbandtvnews.com

CZECH ATTENTION STUDY REVEALS SIGNIFICANT DIFFERENCES ACROSS ADVERTISING FORMATS

Viewer attention can vary significantly depending on ad length, position within an advertising break, and the type of advertising format. These are among the preliminary findings of a pilot project by Omnicom Media, the first study in Central and Eastern Europe to measure real-world attention to TV and video advertising in people’s homes.

Omnicom Media is completing the pilot phase of its attention measurement study, which tracks actual viewer behaviour while audiences are exposed to television and video advertising. The project is being conducted in partnership with technology company Amplified Intelligence and local research partner ResSolution Group. As the first initiative of its kind in Central and Eastern Europe (CEE), it uses continuous attention measurement across a panel of 300 Czech households.

The study captures both active and passive attention across linear TV, connected TV (CTV) and online video, with the aim of establishing a single, comparable metric for evaluating different advertising formats.

According to Zuzana Horáková, Technology Director at Omnicom Media, the first results, covering the period from May to August, already indicate substantial differences in the ability of individual formats, ad lengths and positions within commercial breaks to capture and sustain viewers’ attention.

The pilot phase is now evolving into a longer-term initiative designed to create a continuous data source for the planning and evaluation of video advertising in the Czech market.

What did the preparation for the attention study involve, and how long did it take to get the project up and running?

The preparation involved several months of intensive work. As the first organisation to launch a study of this kind anywhere in the CEE region, our goal was to establish a robust and methodologically rigorous measurement framework. This required extensive technology testing as well as adapting a global methodology to the specific characteristics of the Czech market.

One of our key advantages was Omnicom’s strong international network. Our colleagues in the UK have been successfully conducting this research with the same lead partner for the past three years. Following an initial pilot, they moved to continuous measurement, which has since become an established part of the market data ecosystem.

We therefore had a proven foundation to build on and were able to draw on established methodologies and practical experience.

The commitment of five of our clients, who joined us during the pilot phase at a time when no one knew exactly what the data would reveal, was equally important. Together, we defined the hypotheses, technical setup and analytical framework to ensure the study covered linear TV, CTV and online environments.

How exactly does the measurement work, and how does it differ from existing attention studies?

The fundamental difference lies in our unique approach. We do not rely on self-reported data, laboratory-based models or modelled estimates.

Instead, we use a real-world, technology-enabled panel of 300 households, capturing people’s actual active and passive attention on a second-by-second basis in their natural home environment.

The technology combines advanced facial and gaze detection with audio matching, enabling the system to accurately identify and match the content being viewed in real time.

We measure the market comprehensively and apply Amplified Intelligence’s single, globally standardised methodology across multiple video formats and screens.

Our long-term vision is to establish a unified metric that enables direct and fair comparisons of attention across all media types — from digital and television to other channels — providing comparable data on how much real attention consumers actually devote to advertising.

Who are you partnering with on the research, and how is the project structured from a technical and methodological perspective?

The partnership combines global expertise in attention measurement with strong local research infrastructure.

Amplified Intelligence serves as the project’s technology and methodology partner and is one of the world’s leading authorities in the field of the Attention Economy, ensuring a consistent methodological standard.

From the very beginning, we have discussed the project directly on several occasions with Amplified Intelligence founder Professor Karen Nelson-Field, giving us confidence that the methodology is being implemented to the highest possible standard.

For data collection and operation of the Czech panel, Amplified Intelligence selected ResSolution Group as its local partner. The company has extensive experience with large-scale research programmes, including out-of-home TV audience measurement.

ResSolution Group manages the representative household panel on behalf of Amplified Intelligence, providing the project with the statistical robustness required for detailed segmentation by demographics, channels and specific placement types.

We do not rely on self-reported data, laboratory-based models or modelled estimates. Instead, we use a real-world, technology-enabled panel of 300 households, capturing people’s actual active and passive attention on a second-by-second basis in their natural environment.

The study is designed to compare attention according to ad length, position within a commercial break, channel type and advertising format. How did you decide which parameters were most important to measure?

We started with the real-world questions agencies and advertisers address every day.

We did not want to limit the study to traditional commercial breaks. We therefore examine the impact of different ad lengths, positions within the break, and differences between thematic and generalist TV channels.

At the same time, the study also covers sponsorships, branded in-programme inserts and product placement, allowing us to map the broader advertising ecosystem using one consistent metric.

What could this research bring to the wider market in terms of how television and video advertising are evaluated today?

It represents a fundamental shift from simply measuring an “opportunity to see” an advertisement to measuring the amount of actual attention delivered, in seconds.

Until now, the market has often worked on the assumption that having a viewer in front of the screen automatically equates to 100% exposure.

Our research provides robust, objective data showing how much attention people actually pay to advertising messages, creating opportunities for more effective use of advertising inventory.

Until now, the market has often worked on the assumption that having a viewer in front of the screen automatically equates to 100% exposure. Our research provides robust, objective data showing how much attention people actually pay to advertising messages.

How could this research influence the use of attention as an optimisation metric for TV and video planning in the Czech market?

Attention is moving from an abstract concept to a measurable planning currency.

With this data, media strategies can be optimised not only against reach and frequency, but also directly against cost per attentive second.

This allows us to optimise the balance between shorter and longer ad formats, make more strategic decisions about positioning within commercial breaks, and allocate budgets more precisely across linear TV, CTV and online video.

The objective is to maximise brand memory and advertising impact while maintaining optimal cost efficiency.

How can advertisers use the resulting data?

For advertisers, the data can provide a significant competitive advantage.

Our five pilot clients can already compare their own performance directly against competitors, their category and the market as a whole. The early findings suggest that their decision to participate in the project from the outset has given them a substantial head start.

Advertisers can determine exactly how their creative performs over time by analysing attention decay, identify which formats deliver the greatest amount of attention per unit of media investment, assess whether premium placements generate sufficient incremental value, and understand how the behaviour of their target audience differs from that of the population as a whole.

This enables significantly more precise media investment decisions and helps reduce inefficient media spend.

Are you able to share any preliminary findings?

We are keeping the specific figures and benchmarks exclusive to our clients for now, but the first data from May to August is already challenging a number of long-standing assumptions.

For example, we are seeing major differences in attention-retention curves across different ad lengths, surprising behavioural patterns among specific age groups at different times of day, and highly interesting findings regarding the performance of sponsorships and branded in-programme inserts compared with traditional commercial breaks and online video.

The project also consists of two stages. The pilot measurement phase is currently reaching its conclusion, and we are seamlessly transitioning into a longer-term project together with key partners in the TV market.

The objective is to move towards continuous data collection and track the long-term evolution of advertising attention in the Czech market.

We will be presenting the data soon.

Source: MediaGuru.cz
MEDIAVISION: NORDIC HOUSEHOLDS SPEND €280M ANNUALLY ON ILLEGAL IPTV

Nearly 1.2 million households across the Nordic region now have access to illegal IPTV services, spending an estimated €280 million a year, according to new research from Mediavision.

The figure equates to more than €23 million per month, or approximately €760,000 per day. Households using the services report paying an average of around €20 per month.

Mediavision defines illegal IPTV as paid services offering unauthorised access to extensive TV channel packages and content from multiple streaming platforms.

Its spring 2026 survey found that almost one in ten households in Denmark, Finland, Norway and Sweden had access to illegal IPTV. Sweden has the highest number of affected households, at around 465,000.

Penetration is highest in Norway and Denmark, where approximately 12% of households have access to the services. Sweden follows at 10%, while Finland has the lowest level at 5%.

“Close to 1.2 million Nordic households pay for illegal access to TV and streaming content,” said Adrian Grande, Principal Analyst at Mediavision. “Even at a relatively low monthly cost, the combined spending amounts to a sizable market alongside legal services.”

The regional total is lower than in spring 2025, although the trend varies by market. Mediavision said the declines in Sweden and Finland are clear, while changes in Denmark and Norway are not large enough to confirm a decline.

Grande added that, despite progress in some markets, the scale of illegal IPTV remains significant for the Nordic television and streaming sector.

Source: broadbandtvnews.com

Privacy Overview

This website uses cookies so that we can provide you with the best user experience possible. Cookie information is stored in your browser and performs functions such as recognising you when you return to our website and helping our team to understand which sections of the website you find most interesting and useful.